Signing you in...

Please wait while we verify your authentication

Article · Thursday, October 22, 2026

Cybersecurity · Industry brief

Top three stories shaping Cybersecurity today, written for someone who already works in the industry: regulation, M&A, new entrants, notable filings, and any precedent worth pulling. Cite the trade publication (e.g. trade press, government source, court docket) directly so I can follow up.

By Marius BongartsTech97 editions
← See today's latest
Editions
4 / 97
Generated by AI overnight from public sources, refreshed daily.
Cybersecurity · Industry brief
Thursday, October 22, 2026
Cybersecurity · Industry brief

DSPM consolidation accelerates; MSP multiples hold; cyber insurance tightens

1 min read

DSPM platform consolidation

Data security posture management is becoming a tier-one platform play.

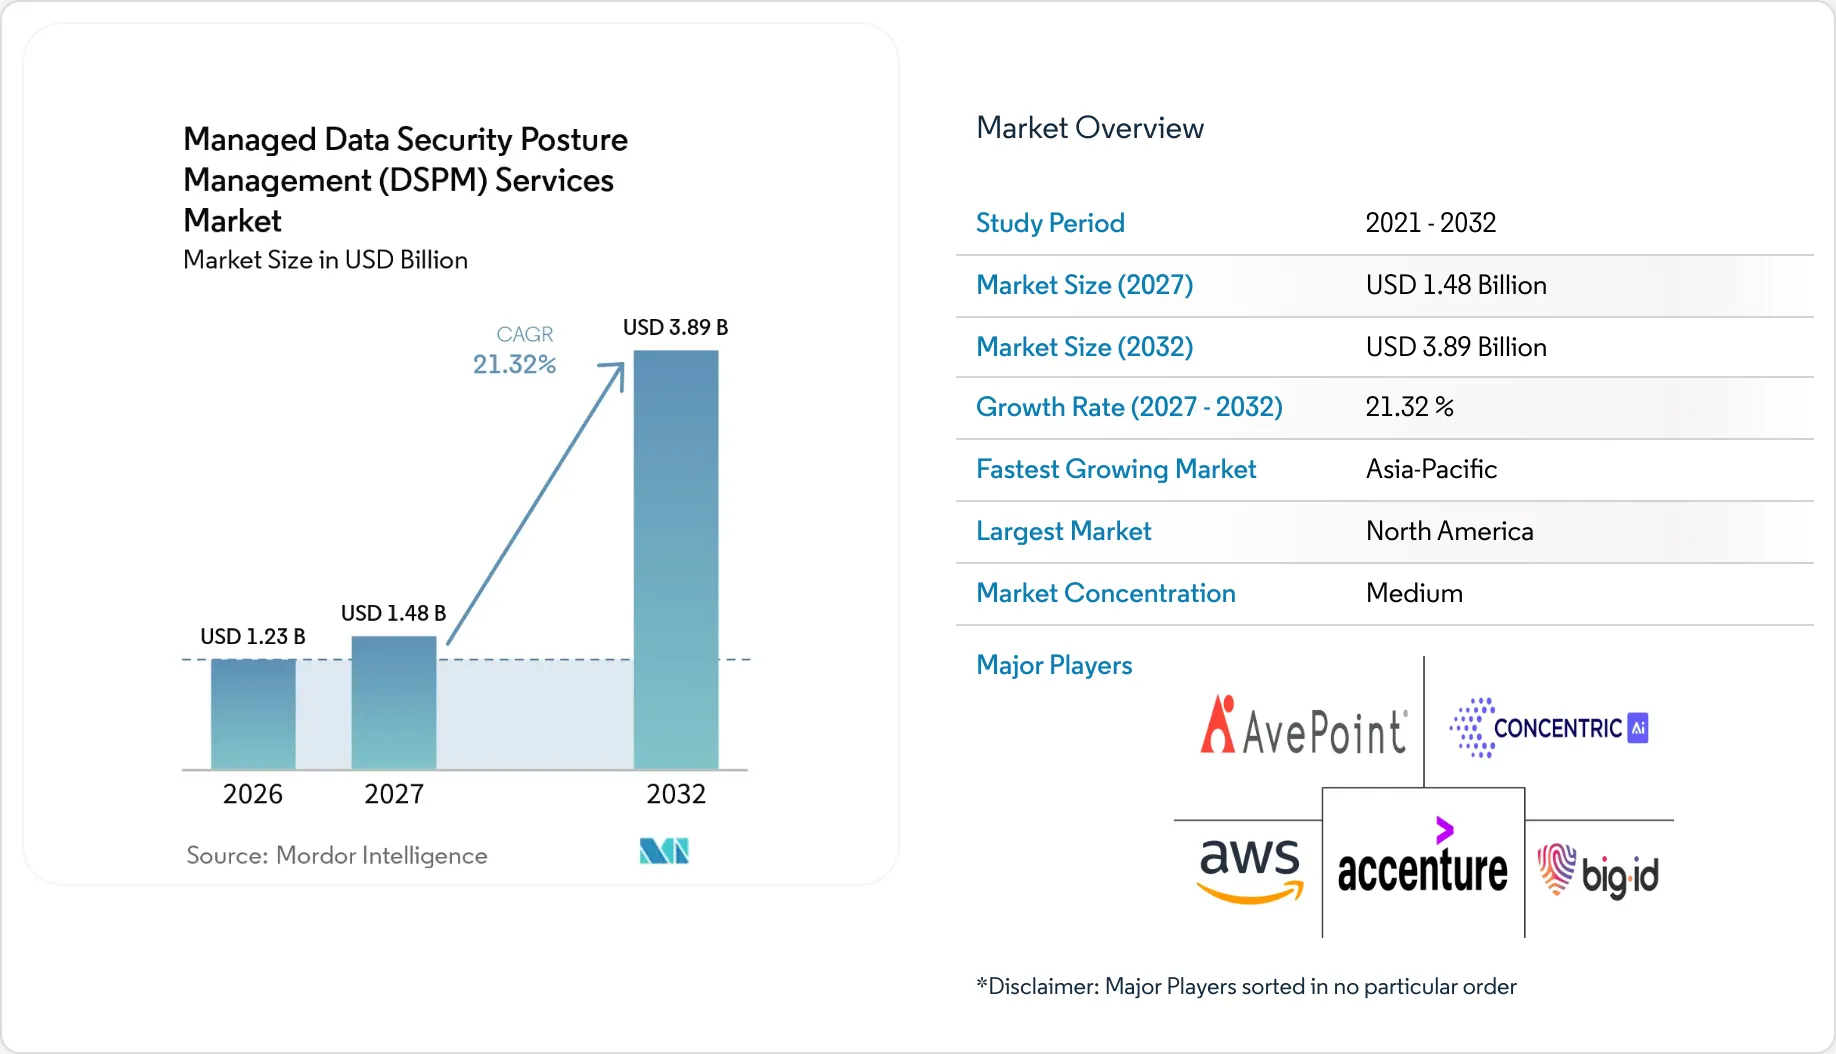
Veeam Software's $1.725 billion acquisition of Securiti AI in October 2025, combined with Forcepoint's Getvisibility deal and Deutsche Telekom's sovereign Cortex launch with Palo Alto Networks, signals that point tools are being absorbed into larger data resilience and governance stacks [Quelle: Mordor Intelligence]. The market is projected to grow at 21.32% CAGR through 2032, with regulatory pressure from DORA, NIS2, and GDPR driving demand for continuous compliance evidence. Fully managed DSPM services alone will expand at 23.61% annually, outpacing professional services growth.

Standalone DSPM vendors now face procurement pressure as buyers consolidate around integrated platforms.

MSP market: steady volume, shifting buyer taste

MSP deal count held at 122 transactions in Q3, but buyer behavior swung sharply.

While M&A volume remained stable at 110 deals and platform valuations anchored at 12–13x EBITDA, buyers increasingly demanded specialization and recurring revenue over generic IT services [Quelle: Drake Star]. IT services fell to 86% of deal count as acquirers pursued communications, software, and commercial services capabilities. Supply surged from founder-owned MSPs in the $2–6M EBITDA band, which may apply modest pressure on add-on multiples holding at 9–10x. Private placements doubled quarter-over-quarter to 12 deals, with PE platforms backing MSP Corp., ECI, PLENTICON, and OryxAlign.

Generalist MSPs without clear capability fit are increasingly sidelined.

Cisco acquires Astrix; NHI becomes consolidation driver

Non-human identity management is now a platform infrastructure gap.

Cisco acquired Astrix Security to fill NHI capability gaps rather than overlay competitive feature parity, underscoring how acquirers now prioritize category ownership and platform consolidation over point-solution buying [Quelle: LinkedIn]. The deal's strategic value hinged on enterprise customer relationships and analyst positioning within the NHI segment—a maturing market infrastructure layer validated by buyer demand. Strategic acquirers now evaluate startups on category maturity, not just feature novelty.

Watch for similar infrastructure-layer consolidation in adjacent identity and API security segments through 2027.
Sources
MSP Market Report Q3 2026 | Drake Star
9 hours ago ... Drake Star MSP Market Update Q3 2026: 110 M&A Deals as Strategic Buyers Pay Up for Specialization ... consolidation. Buyers are getting selective: IT ...
drakestar.com
AI Summary

Drake Star's Q3 2026 MSP Market Update reports 122 total transactions including 110 M&A deals and 12 private placements. Platform valuations remain stable at 12-13x EBITDA with add-ons at 9-10x, sustaining consolidation momentum. Buyer behavior is shifting toward specialization—IT services fell to 86% of deal count as acquirers increasingly pursue communications, software, and commercial services capabilities. Supply is rising from founder-owned MSPs in the $2-6M EBITDA range, which may apply modest pressure on multiples. Private placements doubled quarter-over-quarter to 12 deals, with PE platforms investing in MSP Corp., ECI, PLENTICON, and OryxAlign. Europe accounted for 53% of volume. According to Drake Star Partner Sam Levy, generalist MSPs without clear differentiation are facing headwinds as buyers demand strategic capability fit and recurring revenue.

Visit source
Amit Karp's Post - LinkedIn
12 hours ago ... I often get asked about positioning a cybersecurity startup for acquisition. I think Astrix Security, now part of Cisco joining forces with Cisco is a good ...
linkedin.com
AI Summary

Astrix Security was acquired by Cisco, with the deal positioning non-human identity (NHI) management as a strategic platform gap-filler rather than a competitive feature overlay. According to Alon Jackson's discussion with Amit Karp, Cisco valued the acquisition for its NHI capabilities that complemented rather than duplicated Cisco's existing identity stack. The deal underscores M&A trends in cybersecurity where acquirers prioritize platform consolidation, category ownership (including analyst positioning and market terminology), enterprise customer relationships with large contract values, and technology that addresses market infrastructure needs rather than point solutions. A crowded competitive category in NHI validated the market maturity and infrastructure-level importance of the segment to strategic buyers.

Visit source
Managed Data Security Posture Management (DSPM) Services ...
18 hours ago ... Managed Data Security Posture Management (DSPM) Services Market Size & Share Analysis - Growth Trends and Forecast (2027 - 2032). The Managed Data Security ...
mordorintelligence.com
AI Summary

The managed data security posture management (DSPM) services market is experiencing significant consolidation activity. Veeam Software acquired Securiti AI for USD 1.725 billion in October 2025, combining data resilience with DSPM, privacy, governance, and AI trust capabilities across hybrid, multicloud, and SaaS platforms. Forcepoint announced its agreement to acquire Getvisibility in March 2025 to expand AI-driven data security and risk visibility. Deutsche Telekom and Palo Alto Networks launched Sovereign Cortex with T Security in June 2026, a European data-sovereign cyber defense managed service with encryption key authority retained by Deutsche Telekom. These transactions reflect broader consolidation as platform vendors integrate data posture tools into larger security portfolios, shifting purchasing decisions from point technology selections to platform-wide evaluations. Market growth is driven by escalating regulatory obligations including DORA (applied to EU financial entities since January 2025), NIS2 cybersecurity requirements, and GDPR compliance needs, which are creating demand for continuous data control evidence and managed service delivery. The market is projected to expand from USD 1.48 billion in 2027 to USD 3.89 billion by 2032 at a CAGR of 21.32%, with fully managed DSPM services expanding at 23.61% and professional services at 22.73% through 2032.

Visit source
Compiled overnight by MorningMail.aiDelivered at 02:40 AM